Spring gets all the attention, but it’s not always the best time to sell a house. Yes, more buyers show up, but so do a lot of other sellers.Winter is different. With fewer homes on the

Dated: May 23 2025
Views: 45
 Saving up to buy a home can feel a little intimidating, especially right now. And for many first-time buyers, the idea that you have to put 20% down can feel like a major roadblock.
But that’s actually a common misconception. Here’s the truth.
Unless your specific loan type or lender requires it, odds are you won’t have to put 20% down. There are loan options out there designed to help first-time buyers like you get in the door with a much smaller down payment.
For example, FHA loans offer down payments as low as 3.5%, while VA and USDA loans have no down payment requirements for qualified applicants, like Veterans. So, while putting down more money does have its benefits, it’s not essential. As The Mortgage Reports says:
“. . . many homebuyers are able to secure a home with as little as 3% or even no down payment at all . . . the 20 percent down rule is really a myth.”
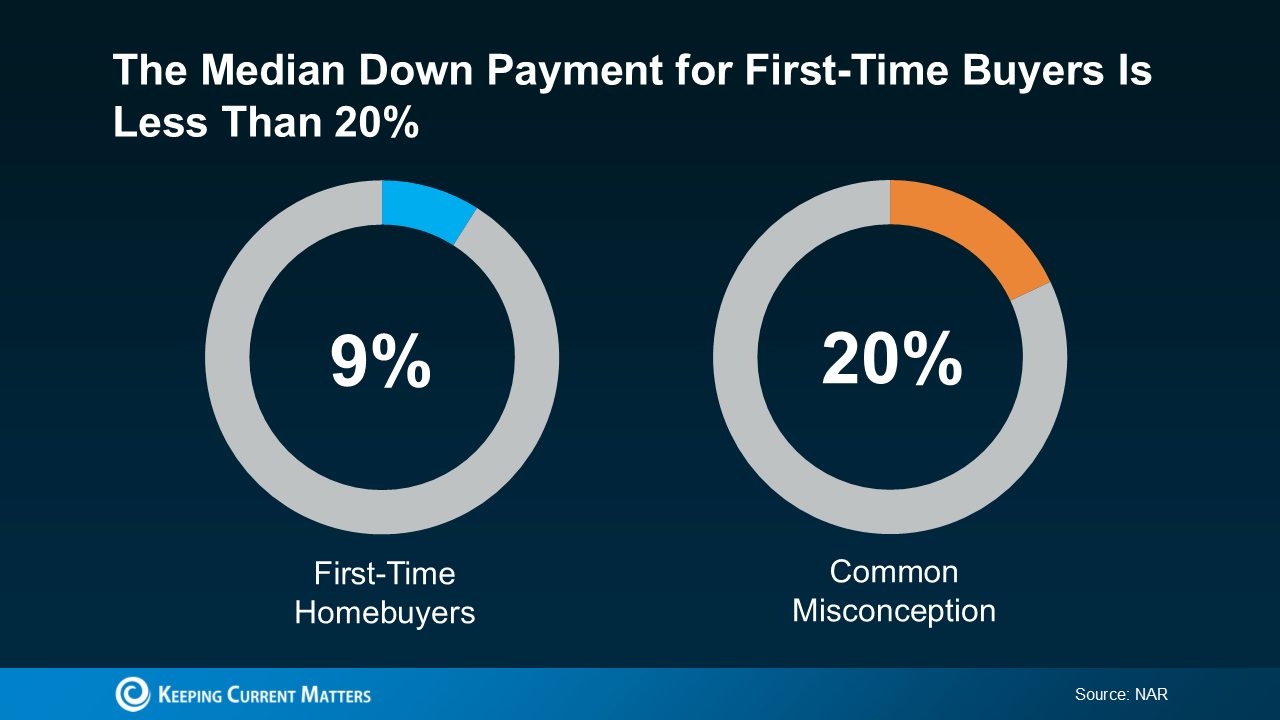
According to the National Association of Realtors (NAR), the median down payment is a lot lower for first-time homebuyers at just 9% (see chart below):
 The takeaway? You may not need to save as much as you originally thought.
And the best part is, there are also a lot of programs out there designed to give your down payment savings a boost. And chances are, you’re not even aware they’re an option.
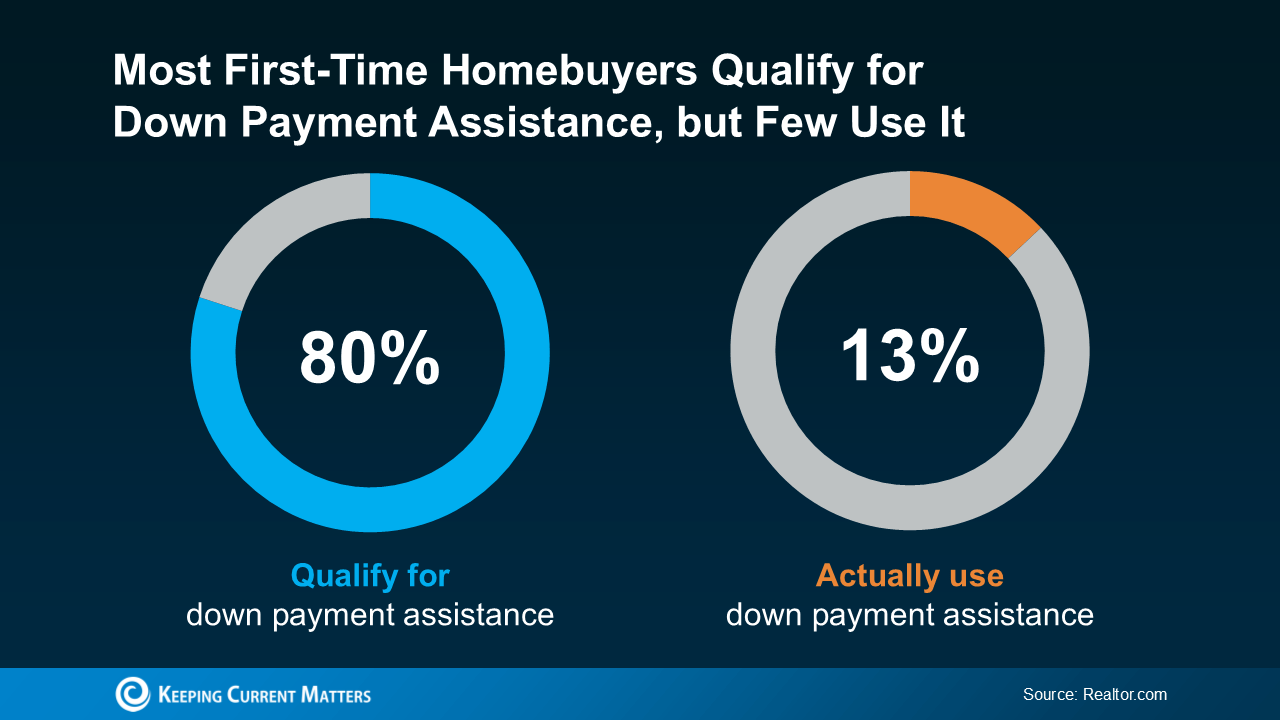
Believe it or not, almost 80% of first-time homebuyers qualify for down payment assistance (DPA), but only 13% actually use it (see chart below):
That’s a lot of missed opportunity. These programs aren’t small-scale help, either. Some offer thousands of dollars that can go directly toward your down payment. As Rob Chrane, Founder and CEO of Down Payment Resource, shares:
“Our data shows the average DPA benefit is roughly $17,000. That can be a nice jump-start for saving for a down payment and other costs of homeownership.”
Imagine how much further your homebuying savings would go if you were able to qualify for $17,000 worth of help. In some cases, you may even be able to stack multiple programs at once, giving what you’ve saved an even bigger lift. These are the type of benefits you don’t want to leave on the table.
Saving up for your first home can feel like a lot, especially if you’re still thinking you have to put 20% down. The truth is that’s a common myth. Many loan options require much less, and there are even programs out there designed to boost your savings too.
To learn more about what’s available and if you’d qualify for any down payment assistance programs, reach out to Rosario and Donna @ truenorthmoves.com. TrueNorth - “Helping you find—and finance—your way home!”
Your Real Estate Journey. Streamlined with Dual Expertise.At TrueNorth Group, we're more than just a real estate team—we’re a fully licensed duo in both real estate and mortgage lending, o....
Spring gets all the attention, but it’s not always the best time to sell a house. Yes, more buyers show up, but so do a lot of other sellers.Winter is different. With fewer homes on the
When the holidays roll around, travel plans, family gatherings, and all the chaos of the season may make you think it’s better to pull your listing off the market or to wait until 2026 to
If you’ve served in the military (or if your spouse has), you have access to one of the most powerful homebuying tools out there. The chance to buy a home without having a down payment
Mortgage rates have been the monster under the bed for a while. Every time they tick up, people flinch and say, “Maybe I’ll wait.” But here’s the twist. Waiting for
 The data relating to real estate for sale on this website comes in part from the IDX Program of Garden State Multiple Listing Service, L.L.C. and eXp Realty in Central Jersey. Real estate listings held by other brokerage firms are marked as IDX listing. Information deemed reliable but not guaranteed. Copyright © 2026 Garden State Multiple Listing Service, L.L.C. All rights reserved. This information is being provided for Consumer's personal, non-commercial use and may not be used for any purpose
other than to identify prospective properties Consumers may be interested in purchasing
The dissemination of listings on the website does not constitute the consent required by N.J.A.C. 11.5.6.1 (n) for the advertisement of listings exclusively for sale by another broker. Any such consent must be obtained in writing from the listing broker.
Show More...
 The data relating to real estate for sale on this web-site comes in part from the Internet Listing Display database of the ALL JERSEY MULTIPLE LISTING SYSTEM, INC. Real estate listings held by brokerage firms other than this site-owner are marked with the ILD logo. The ALL JERSEY MULTIPLE LISTING SYSTEM, INC. does not warrant the accuracy, quality, reliability, suitability, completeness, usefulness or effectiveness of any information provided.
The information being provided is for consumers' personal,
non-commercial use and may not be used for any purpose other than to identify properties the consumer may be interested in purchasing or renting.
Copyright 2026, ALL JERSEY MULTIPLE LISTING SYSTEM, INC. All rights reserved. The ALL JERSEY MULTIPLE LISTING SYSTEM, INC retains all rights, title and interest in and to its trademarks, service marks and copyrighted material.
Show More...
 All information is believed to be accurate but is not guaranteed. Protected by Copyright© 2026 and is owned either by the Monmouth County Association of REALTORS; or by the developers of the software, Kunversion, LLC. All rights reserved. Each office independently owned and operated.
The New Jersey Real Estate Commission requires every licensed broker or salesperson with whom you list your property to give you a copy of this notice. The purpose is to help you comply with the New Jersey Law
Against Discrimination (the "LAD) and federal laws prohibiting discrimination in the sale or rental of real property.
In New Jersey, it is illegal to discriminate against a prospective or current buyer or tenant because of race, creed, color, national origin, sex, gender identity or expression, marital status, civil union status, or source of lawful income used for mortgage or rental payments. It is also illegal to place any advertisement or make any statements or utterances that express, directly or indirectly, any limitations to offer housing based on any of those characteristics.
Show More...
 The data relating to the real estate for sale on this web site comes in part from the Internet Data Exchange Program of the NJMLS. Real estate listings held by brokerage firms other than eXp Realty in Central Jersey are marked with the Internet Data Exchange logo and information about them includes the name of the listing brokers. Some properties listed with the participating brokers do not appear on this website at the request of the seller. Listings of brokers that do not participate in Internet Data Exchange do not appear on this website. All information deemed reliable but not guaranteed.
Last date updated: September 22, 2026 5:12 AM UTC Source: New Jersey Multiple Listing Service, Inc. "© 2026 New Jersey Multiple Listing Service, Inc. All rights reserved."
 © BRIGHT, All Rights Reserved
Information Deemed Reliable But Not Guaranteed
The data relating to real estate for sale on this website appears in part through the BRIGHT Internet Data Exchange program, a voluntary cooperative exchange of
property listing data between licensed real estate brokerage firms in which
participates, and is provided by BRIGHT through a licensing agreement.
The information provided by this website is for the personal,
non-commercial use of consumers and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Data last updated: September 22, 2026 3:50 AM UTC
Some properties which appear for sale on this website may no longer be available
because they are under contract, have Closed or are no longer being offered for sale.
Some real estate firms do not participate in IDX and their listings do not appear on this website. Some properties listed with participating firms do not appear on this website at the request of the seller.
Show More...
